Protocol Lending Guide: Complete Guide
Introduction
Decentralised Finance (DeFi) lending has emerged as one of the most transformative innovations in the cryptocurrency ecosystem. It offers unprecedented opportunities for both lenders and borrowers. They can participate in a truly global, permissionless financial system. In 2025, DeFi lending protocols have matured significantly. They provide institutional-grade security, competitive yields, and innovative features. Traditional banking systems cannot match these capabilities.
The DeFi lending landscape has evolved from experimental protocols to sophisticated financial infrastructure. It processes billions of dollars in lending activity across multiple blockchain networks. This evolution has created opportunities for users to earn attractive yields on their cryptocurrency holdings. They provide essential liquidity to the broader DeFi ecosystem. This enables everything from leveraged trading to complex yield farming strategies.
Professional DeFi lending strategies have become increasingly sophisticated. They incorporate risk management techniques, protocol diversification, and advanced yield optimisation methods. Institutional investors use these to maximise returns. They manage exposure to smart contract risks, market volatility, and protocol governance changes. The most successful DeFi lenders understand the importance of due diligence. They focus on risk assessment and strategic allocation across multiple protocols and blockchain networks.
This comprehensive guide examines every aspect of DeFi lending. It covers basic concepts and platform selection. It includes advanced strategies and risk management techniques. Whether you're new to DeFi or seeking to optimise your existing lending activities, this guide provides the knowledge and tools necessary. You can participate safely and profitably in the decentralised lending ecosystem.
The DeFi lending landscape has evolved from experimental protocols to battle-tested platforms managing billions of dollars in total value locked (TVL). Major protocols like Aave, Compound, and Sky have demonstrated remarkable resilience through multiple market cycles, establishing themselves as the backbone of decentralised finance. These platforms offer lending and borrowing services that operate 24/7 without intermediaries, providing users with complete control over their financial activities.
For lenders, DeFi protocols offer attractive yields that often exceed traditional savings accounts by significant margins. Interest rates are determined by market dynamics of supply and demand, creating efficient pricing mechanisms that reward lenders with competitive returns. The transparency of blockchain technology ensures that all lending activities are verifiable and auditable, providing unprecedented visibility into protocol operations and risk factors.
Borrowers benefit from instant access to liquidity without lengthy approval processes or credit checks. By providing cryptocurrency collateral, users can access loans in minutes rather than weeks, enabling capital-efficiency strategies previously impossible in traditional finance. The programmable nature of smart contracts ensures that loan terms are executed automatically, eliminating counterparty risk and reducing operational costs.
The technological infrastructure supporting DeFi lending has reached new levels of sophistication. Advanced features like flash loans, credit delegation, and cross-chain compatibility have expanded the possibilities for complex financial strategies. Insurance protocols and safety modules provide additional protection for user funds, while governance tokens enable community-driven protocol development and risk management.
Understanding DeFi lending requires familiarity with key concepts such as overcollateralisation, liquidation mechanisms, and yield farming strategies. This comprehensive guide will equip you with the knowledge needed to navigate the DeFi lending ecosystem safely and profitably, whether you're seeking to earn passive income on your cryptocurrency holdings or access liquidity for investment opportunities.
Blockchain lending has revolutionised the traditional financial system by enabling peer-to-peer lending without intermediaries. Decentralised lending protocols have matured significantly, offering competitive yields and innovative features that traditional banks cannot match.
This comprehensive guide covers everything you need to know about decentralised finance lending, from basic concepts to advanced strategies, helping you navigate the digital asset lending landscape safely and profitably.
Overview
Decentralised Finance (DeFi) lending has emerged as one of the most transformative innovations in the cryptocurrency ecosystem. It fundamentally changes how individuals and institutions access credit. It changes how they generate yield from digital assets. Unlike traditional banking systems that rely on centralised intermediaries, DeFi lending operates through smart contracts on blockchain networks. This enables permissionless, transparent, and globally accessible financial services.
The DeFi lending landscape has matured significantly from its experimental beginnings. Protocols now manage billions of dollars in total value locked (TVL). They offer sophisticated financial products that rival traditional banking services. This evolution has been driven by technological improvements, regulatory clarity, and growing institutional adoption. This has brought professional-grade security and compliance standards to decentralised protocols.
Modern DeFi lending protocols offer compelling advantages over traditional financial services. These include higher yields for lenders, instant loan approvals for borrowers, and complete transparency in operations. The elimination of intermediaries reduces costs. It enables 24/7 global access to financial services. This makes DeFi lending particularly attractive for underserved populations and regions with limited banking infrastructure. It provides competitive alternatives for users in developed markets seeking better returns on their capital.
The technological foundation of DeFi lending relies on smart contracts. These automatically execute lending agreements. They calculate interest rates based on supply and demand dynamics. They manage collateral requirements without human intervention. This automation reduces counterparty risk. It eliminates the need for credit checks. It enables instant settlement of transactions across global markets. This ensures consistent and predictable execution of lending terms regardless of market conditions.
Risk management in DeFi lending has evolved considerably, with protocols implementing sophisticated mechanisms including over-collateralisation requirements, automated liquidation systems, insurance funds, and governance tokens that align stakeholder incentives. Understanding these risk mitigation strategies is crucial for participants seeking to maximise returns while protecting their capital in this rapidly evolving ecosystem where new protocols and features are constantly being developed.
The regulatory landscape surrounding DeFi lending continues to develop, with major jurisdictions working to establish frameworks that balance innovation with consumer protection while preserving the decentralised nature of these protocols. This regulatory evolution has encouraged institutional participation and improved the overall security and reliability of DeFi lending platforms, making them more attractive to mainstream investors while maintaining permissionless access.
Yield generation opportunities in DeFi lending extend beyond simple interest earning, with protocols offering additional rewards through governance tokens, liquidity mining programs, and yield farming strategies that can significantly enhance returns. These mechanisms introduce additional complexity and risk that require careful evaluation and management, but they also provide opportunities for sophisticated users to optimise their returns through strategic participation in protocol governance.
The integration of DeFi lending with other financial services has created a composable ecosystem where users can combine lending, trading, derivatives, and insurance products to create sophisticated investment strategies. This composability represents one of DeFi's most powerful features, enabling innovation and efficiency that would be impossible in traditional financial systems while allowing users to customise their financial strategies according to their specific needs and risk tolerance.
Interest rate mechanisms in DeFi lending protocols operate through algorithmic models that automatically adjust rates based on supply and demand dynamics, creating efficient markets that respond instantly to changing conditions without human intervention. These automated systems ensure that lenders receive competitive returns while borrowers access fair pricing based on real-time market conditions, creating a more efficient and responsive financial system than traditional banking infrastructure can provide.
The technological foundation of DeFi lending relies on smart contracts that automatically execute lending agreements, calculate interest rates based on supply and demand dynamics, and manage collateral requirements without human intervention. This automation reduces counterparty risk, eliminates the need for credit checks, and enables instant settlement of transactions across global markets.
Risk management in DeFi lending has evolved considerably, with protocols implementing sophisticated mechanisms including over-collateralisation, liquidation systems, insurance funds, and governance tokens that align stakeholder incentives. Understanding these risk mitigation strategies is crucial for participants seeking to maximise returns while protecting their capital in this rapidly evolving ecosystem.
The regulatory landscape surrounding DeFi lending continues to develop, with major jurisdictions working to establish frameworks that balance innovation with consumer protection. This regulatory evolution has encouraged institutional participation and improved the overall security and reliability of DeFi lending platforms, making them more attractive to mainstream investors.
Yield generation opportunities in DeFi lending extend beyond simple interest earning, with protocols offering additional rewards through governance tokens, liquidity mining programs, and yield farming strategies. These mechanisms can significantly enhance returns but also introduce additional complexity and risk that require careful evaluation and management.
The integration of DeFi lending with other financial services has created a composable ecosystem where users can combine lending, trading, derivatives, and insurance products to create sophisticated investment strategies. This composability represents one of DeFi's most powerful features, enabling innovation and efficiency that would be impossible in traditional financial systems.
Interest rate mechanisms in DeFi lending protocols operate through algorithmic models that automatically adjust rates based on supply and demand dynamics, creating efficient markets that respond instantly to changing conditions. These automated systems eliminate the need for human intervention in rate setting, ensuring that lenders receive competitive returns while borrowers access fair pricing based on real-time market conditions.
The global accessibility of DeFi lending platforms has democratised access to financial services, enabling users from any country with internet access to participate in sophisticated lending markets previously available only to institutional investors. This democratisation has created new opportunities for wealth generation and financial inclusion, particularly in regions with underdeveloped traditional banking infrastructure.
Security considerations in DeFi lending require careful attention to smart contract audits, protocol governance structures, and insurance mechanisms that protect user funds. Whilst the decentralised nature of these protocols eliminates traditional counterparty risks, it introduces new categories of technical and operational risks that users must understand and manage through proper due diligence and risk assessment practices.
This comprehensive guide provides everything you need to understand and participate in DeFi lending successfully, from fundamental concepts and platform selection to advanced strategies and risk management. Whether you're a newcomer seeking to earn yield on your cryptocurrency holdings or an experienced investor looking to optimise your DeFi strategy, this guide will help you navigate the complexities and opportunities of decentralised lending.
What is Decentralised Finance Lending?
Blockchain lending refers to the practice of lending and borrowing cryptocurrencies through decentralised protocols built on blockchain networks, primarily Ethereum. Unlike traditional lending, DeFi eliminates intermediaries, such as banks, allowing users to interact directly with smart contracts.
Key Characteristics of Blockchain Lending
- Permissionless Access: Anyone with a crypto wallet can participate without KYC requirements
- Transparent Operations: All transactions and protocol mechanics are visible on-chain
- Programmable Money: Smart contracts automate lending processes and interest calculations
- Global Accessibility: Available 24/7 worldwide without geographical restrictions
- Composability: Protocols can interact with each other, creating complex financial products
How Decentralised Finance Lending Works
Smart contract lending operates through liquidity pools where lenders deposit their assets to earn interest, while borrowers can take loans by providing collateral. The process is governed by smart contracts that automatically execute lending terms.
The Lending Process
- Deposit Assets: Lenders deposit cryptocurrencies into lending pools
- Earn Interest: Deposited assets automatically earn interest from borrower payments
- Receive Pool Tokens: Lenders get tokens representing their share of the pool
- Withdraw Anytime: Most protocols allow withdrawal of funds at any time
The Borrowing Process
- Provide Collateral: Borrowers deposit collateral — protocol minimums for major assets sit around 125-135% of the loan, and cautious borrowers hold 150-200%
- Borrow Assets: Take loans against collateral up to the maximum loan-to-value ratio
- Pay Interest: Interest accrues continuously and must be paid to maintain the loan
- Avoid Liquidation: Maintain adequate collateral ratio to prevent liquidation
Top Lending Protocols
1. Aave
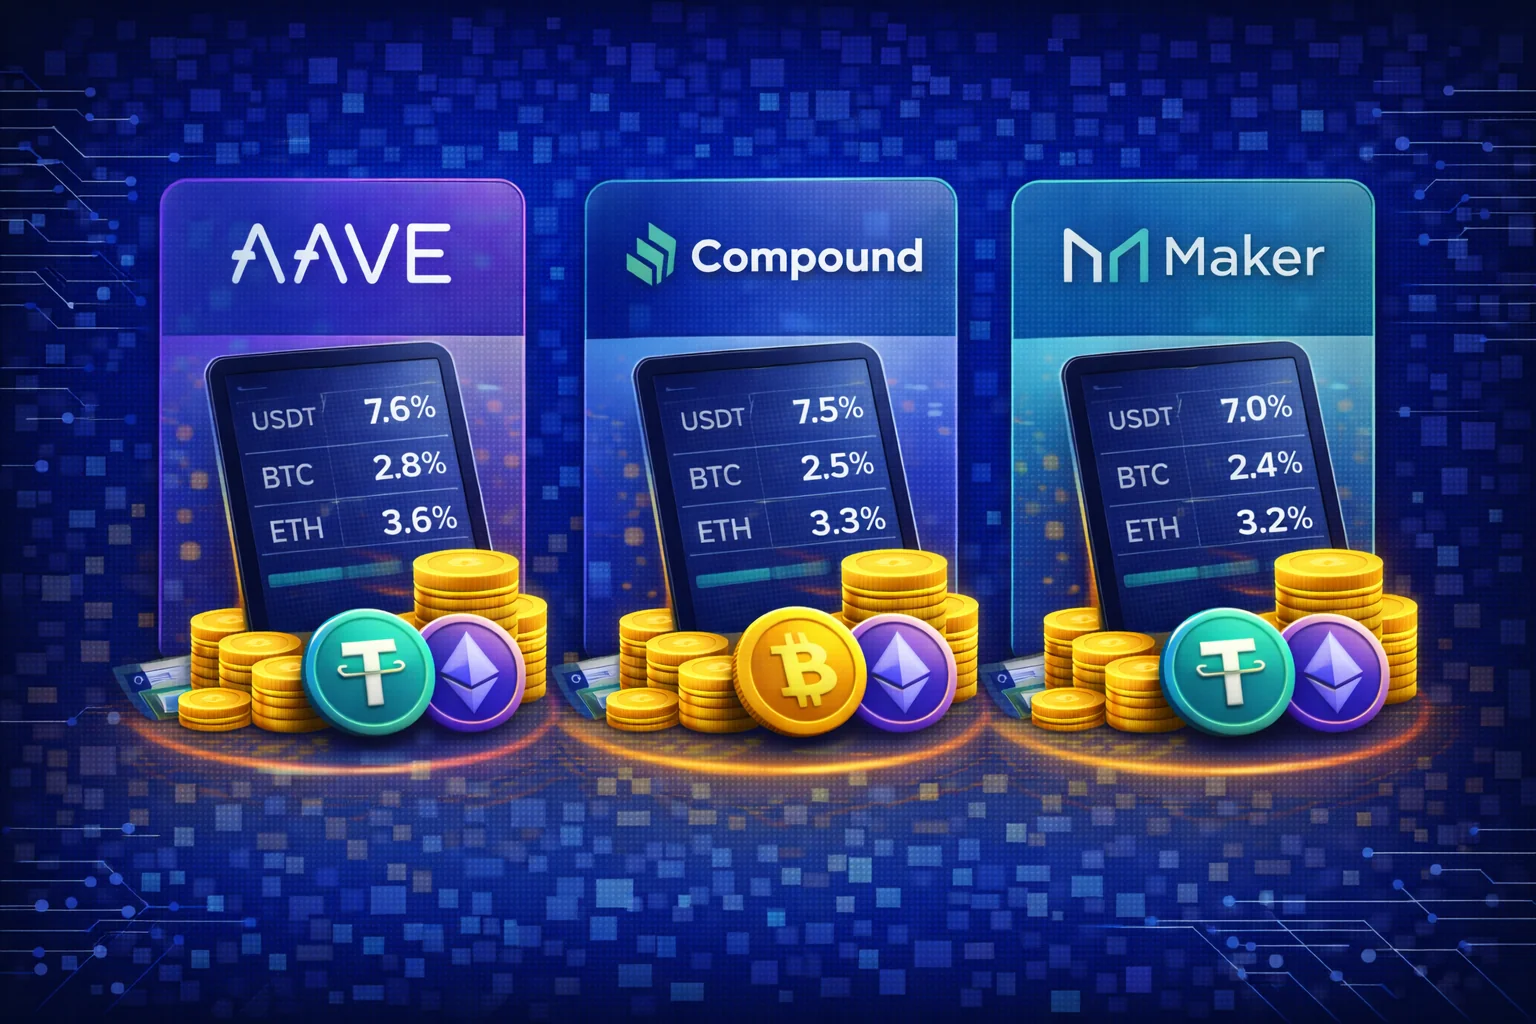
Aave is the largest digital asset lending protocol, with TVL still measured in the tens of billions. It offers variable interest rates only — stable-rate borrowing was retired by governance in January 2024 — plus flash loans and credit delegation.
Aave V4 launched on Ethereum mainnet on 30 March 2026 after a binding on-chain governance vote and a 345-day security-review cycle covering four audit firms, four independent experts, and a 900+ participant public contest. V4 introduces a hub-and-spoke architecture that lets separate lending markets share a single liquidity pool, and lets spokes be designed for tokenised real-world-asset collateral alongside the familiar variable-rate model. Initial deployment supports USDT, USDC, EURC, XAUt, cbBTC, frxUSD, USDG, plus liquid-staking and restaking collateral from Lido, EtherFi, Kelp, Ethena, and Lombard.
- Supported Assets: 30+ cryptocurrencies including ETH, USDC, DAI, WBTC; V4 adds the RWA-friendly set above
- Key Features: Flash loans, variable rates only, credit delegation, governance token (AAVE), V4 hub-and-spoke for market separation
- Interest Rates: Variable rates roughly in the 0.5–15% range depending on asset and utilisation; the initial V4 spokes are all variable-rate
- Safety Features: Insurance fund, decentralised governance, battle-tested smart contracts, and the V4 security-review track described above
2. Compound
Compound pioneered algorithmic interest rates in DeFi and remains one of the most trusted lending protocols. It features a simple interface and has undergone extensive auditing.
- Supported Assets: 15+ major cryptocurrencies
- Key Features: Algorithmic interest rates; Compound III markets with one borrowable base asset each (cTokens survive only in the retired V2); COMP governance token
- Interest Rates: Dynamic rates based on supply and demand
- Advantages: Simple interface, proven track record, strong security
3. Sky
Sky (formerly MakerDAO) issues the USDS and DAI stablecoins against collateral locked in vaults. DAI upgrades 1:1 to USDS, and the Sky Savings Rate is paid on sUSDS.
- Primary Function: USDS and DAI minting against vault collateral
- Collateral Types: ETH, WBTC, USDC, and other approved assets
- Stability Fee: set per vault type by governance and changed by vote (not quoted here)
- Governance: SKY token holders control protocol parameters
4. Morpho
Morpho is now a standalone lending protocol — isolated markets and curated vaults — and the second-largest by TVL at about $7.6bn (DefiLlama, 4 August 2026). Its earlier peer-to-peer optimiser that sat on top of Aave and Compound has been retired.
- Design: permissionless isolated markets, each with one collateral and one loan asset
- Vaults: curated vaults allocate deposits across markets
- Benefits: risk is contained per market rather than pooled
- Status: Growing rapidly with institutional adoption
Protocol-Based Lending Strategies
Conservative Lending Strategy
Focus on established protocols and stablecoins for steady, low-risk returns:
- Asset Selection: USDC, USDT, DAI on Aave or Compound
- Expected Returns: 3-8% APY with minimal volatility risk
- Risk Level: Low to moderate
- Time Commitment: Minimal monitoring required
Yield Optimisation Strategy
Actively move funds between protocols to maximise returns:
- Tools: Use yield aggregators like Yearn Finance or Beefy
- Approach: Automatically compound rewards and optimise for highest APY
- Expected Returns: 8-15% APY depending on market conditions
- Risk Level: Moderate due to smart contract complexity
Leveraged Lending Strategy
Use borrowed funds to increase lending positions for higher returns:
- Method: Deposit collateral, borrow stablecoins, lend borrowed funds
- Leverage: 2-3x leverage depending on risk tolerance
- Expected Returns: 15-25% APY in favourable conditions
- Risk Level: High due to liquidation risk and market volatility
Understanding Smart Contract Lending Risks
Smart Contract Risk
Smart contracts may contain bugs or vulnerabilities that could lead to fund loss:
- Mitigation: Use audited protocols with proven track records
- Research: Check audit reports and bug bounty programs
- Diversification: Spread funds across multiple protocols
Liquidation Risk
Borrowers face liquidation if collateral value drops below required ratios:
- Prevention: Maintain conservative collateral ratios (200%+)
- Monitoring: Set up alerts for collateral ratio changes
- Emergency Plans: Keep funds available to add collateral quickly
Impermanent Loss
When providing liquidity to AMM pools, token price divergence can cause losses:
- Understanding: Loss occurs when token prices change relative to each other
- Mitigation: Use stablecoin pairs or correlated assets
- Compensation: Trading fees and rewards may offset impermanent loss
Regulatory Risk
Changing regulations could impact DeFi protocol operations:
- Monitoring: Stay informed about regulatory developments
- Compliance: Use protocols with strong legal frameworks
- Diversification: Consider protocols in different jurisdictions
Getting Started with Protocol Lending
Step 1: Set Up Your Wallet
Choose a compatible wallet that supports DeFi interactions:
- MetaMask: Most popular browser extension wallet
- WalletConnect: Connect mobile wallets to DeFi apps
- Hardware Wallets: Ledger or Trezor for maximum security
Step 2: Fund Your Wallet
Acquire cryptocurrencies and ETH for gas fees:
- Exchanges: Buy crypto on Kraken or Binance
- Gas Fees: Keep 0.1-0.5 ETH for transaction costs
- Stablecoins: Start with USDC or USDT for lower volatility
Step 3: Choose a Protocol
Start with established protocols for your first protocol-based lending experience:
- Beginners: Aave or Compound for simplicity and security
- Advanced: Explore Morpho or specialised protocols
- Research: Compare interest rates and features
Step 4: Make Your First Deposit
Start small to familiarise yourself with the process:
- Amount: Begin with $100-500 to learn the interface
- Asset: Choose a stablecoin for predictable returns
- Confirmation: Verify transaction details before confirming
Advanced Protocol Lending Concepts
Flash Loans
Flash loans allow borrowing large amounts without collateral, provided the loan is repaid within the same transaction:
- Use Cases: Arbitrage, liquidations, collateral swapping
- Requirements: Advanced programming knowledge
- Risks: Failed transactions result in gas fee loss
Credit Delegation
Aave's credit delegation allows users to delegate borrowing power to others:
- Mechanism: Depositors can allow others to borrow against their collateral
- Benefits: Earn fees from delegation while maintaining collateral ownership
- Risks: Delegated borrower's default affects your collateral
Why There Is No Rate Switching
Older guides describe switching between variable and stable rates on Aave. That option was retired by governance in January 2024, when every stable-rate position was converted to variable, and Aave V3 and V4 offer variable rates only. If a page tells you to switch modes, it is describing a mechanism that no longer exists.
Tax Considerations for DeFi Lending
Income Recognition
Interest earned from digital asset lending is generally considered taxable income:
- Timing: Income recognised when earned, not when withdrawn
- Valuation: Use fair market value at time of earning
- Records: Keep detailed records of all transactions
Capital Gains
Token price changes may trigger capital gains or losses:
- Pool Tokens: Changes in pool token value may be taxable
- Rewards: Governance tokens received as rewards are taxable
- Professional Help: Consult tax professionals for complex situations
DeFi Lending vs Traditional Lending
Advantages of Digital Asset Lending
Protocol-based lending offers several advantages over traditional banking:
- Higher Yields: DeFi protocols often offer 3-15% APY compared to 0.1-2% in traditional savings
- Global Access: Available 24/7 worldwide without geographical restrictions
- No Credit Checks: Lending based on collateral, not credit history
- Transparency: All transactions and rates visible on blockchain
- Programmable: Automated processes reduce human error and bias
- Composability: Protocols can interact to create complex financial products
- Permissionless: No KYC requirements or account approvals needed
Disadvantages of Blockchain Lending
However, digital asset lending also has limitations:
- Technical Complexity: Requires understanding of wallets, gas fees, and smart contracts
- No Insurance: Most protocols lack traditional deposit insurance
- Volatility Risk: Cryptocurrency price fluctuations affect returns
- Smart Contract Risk: Bugs or exploits can lead to fund loss
- Regulatory Uncertainty: Unclear legal status in many jurisdictions
- Gas Fees: Ethereum network fees can be expensive during congestion
- Irreversible Transactions: Mistakes cannot be easily reversed
Security Best Practices for DeFi Lending
Wallet Security
Protecting your wallet is crucial for DeFi safety:
- Hardware Wallets: Use Ledger or Trezor for large amounts
- Seed Phrase Security: Store recovery phrases offline in multiple secure locations
- Regular Updates: Keep wallet software updated to latest versions
- Phishing Protection: Always verify website URLs and never share private keys
- Multi-Signature: Consider multi-sig wallets for institutional amounts
Protocol Due Diligence
Research protocols thoroughly before depositing funds:
- Audit Reports: Review security audits from reputable firms
- Track Record: Check protocol history and past security incidents
- Team Transparency: Research the development team and their backgrounds
- Community: Active community and developer engagement
- Bug Bounties: Protocols with active bug bounty programs
- Insurance: Some protocols offer insurance coverage
Risk Management Strategies
Implement proper risk management for DeFi protocols:
- Diversification: Spread funds across multiple protocols and assets
- Position Sizing: Never invest more than you can afford to lose
- Regular Monitoring: Check positions and protocol health regularly
- Exit Strategy: Have clear criteria for when to withdraw funds
- Emergency Fund: Keep funds available for gas fees and emergencies
Layer 2 and Alternative Chain Lending
Polygon (POL, formerly MATIC) Lending
Polygon offers faster and cheaper protocol lending alternatives:
- Protocols: Aave V3 and Compound III (QuickSwap is a DEX, not a lender)
- Benefits: Sub-cent transaction fees and instant confirmations
- Yields: no longer higher than mainnet — Aave USDC paid less on Polygon than on Ethereum when read in August 2026, the incentive programmes having ended
- Bridge Risk: Consider risks when moving assets between chains
Arbitrum and Optimism
Ethereum Layer 2 solutions provide scaling for protocol lending:
- Arbitrum: Aave V3 and Compound III (GMX is a perpetuals exchange, not a lender)
- Optimism: Aave V3 and smaller native lending markets
- Security: Inherit Ethereum's security while reducing costs
- Liquidity: Growing but still smaller than mainnet
Avalanche and Other Chains
Alternative blockchains offer unique lending opportunities:
- Avalanche: Benqi and Aave V3 (LFJ, formerly Trader Joe, is a DEX with no lending market)
- Solana: Kamino Lend, Jupiter Lend and Save (formerly Solend); Mango Markets has wound down
- BNB Chain: Venus Protocol and Lista Lending (PancakeSwap has no lending product)
- Considerations: Different risk profiles and decentralisation levels
Yield Farming and Liquidity Mining
Understanding Yield Farming
Yield farming combines lending with additional reward mechanisms:
- Concept: Earn lending interest plus protocol governance tokens
- Rewards: Additional APY from token incentives
- Complexity: Requires understanding of multiple protocols
- Risks: Impermanent loss and token price volatility
Liquidity Mining Strategies
Optimise returns through strategic liquidity provision:
- Stablecoin Pairs: USDC/USDT pairs for minimal impermanent loss
- Correlated Assets: ETH/stETH or similar correlated pairs
- Reward Tokens: Evaluate tokenomics of reward tokens
- Auto-Compounding: Use yield aggregators for automatic reinvestment
Popular Yield Aggregators
Yield aggregators automate complex DeFi strategies:
- Yearn Finance: Pioneer in automated yield optimisation
- Beefy Finance: Multi-chain yield farming platform
- Harvest Finance: Automated farming with FARM token rewards
- Convex Finance: optimises Curve Finance yields
Institutional Protocol Lending
Institutional Adoption Trends
Traditional finance is increasingly embracing protocol lending:
- Banks: JPMorgan, Goldman Sachs exploring DeFi integration
- Asset Managers: Fidelity, BlackRock offering crypto services
- Hedge Funds: Using DeFi for yield generation and arbitrage
- Insurance: Nexus Mutual and other DeFi insurance protocols
Compliance and Regulation
Regulatory frameworks are evolving for protocol lending:
- KYC/AML: Some protocols implementing identity verification
- Licensing: Regulatory licences for DeFi service providers
- Reporting: Tax reporting requirements for DeFi activities
- Consumer Protection: Investor protection measures
Institutional-Grade Protocols
Protocols designed for institutional participation:
- Maple Finance: Institutional lending with credit assessment
- TrueFi: uncollateralised lending to institutions — effectively inactive, with TVL near zero (DeFiLlama, August 2026)
- Goldfinch: Real-world lending through DeFi (winding down to maintenance mode, 2026)
- Centrifuge: Asset tokenisation and institutional lending
Troubleshooting Common Issues
Transaction Failures
Common reasons for failed DeFi transactions:
- Insufficient Gas: Set appropriate gas limits for complex transactions
- Slippage: Adjust slippage tolerance for volatile markets
- Network Congestion: Wait for lower network activity or increase gas price
- Smart Contract Issues: Protocol may be paused or experiencing issues
Stuck Transactions
Solutions for transactions that won't confirm:
- Speed Up: Increase gas price to accelerate transaction
- Cancel: Send 0 ETH to yourself with the same nonce and higher gas
- Wait: Transactions eventually expire if gas price is too low
- Reset Account: Reset MetaMask account to clear pending transactions
Withdrawal Issues
Common problems when withdrawing from lending protocols:
- Liquidity Shortage: Protocol may have insufficient liquidity
- Cooldown Periods: Some protocols have withdrawal delays
- Minimum Amounts: Check minimum withdrawal requirements
- Gas Estimation: Ensure sufficient ETH for withdrawal gas fees
Future of DeFi Lending
Technological Innovations
Emerging technologies shaping protocol-based lending's future:
- Zero-Knowledge Proofs: Privacy-preserving lending protocols
- Account Abstraction: Simplified user experiences
- AI Integration: Automated risk assessment and optimisation
- Cross-Chain Protocols: Lending markets that operate across several networks rather than a single chain
Institutional Adoption
Traditional financial institutions are increasingly exploring blockchain lending:
- Compliance: Development of regulatory-compliant DeFi protocols
- Integration: Traditional banks offering digital asset lending services
- Liquidity: Institutional participation increasing overall liquidity
- Infrastructure: Professional custody and risk management solutions
Cross-Chain Lending
Multi-chain protocols are expanding lending opportunities:
- Networks: Ethereum, Polygon, Avalanche, Arbitrum integration
- Benefits: Lower fees and faster transactions
- Challenges: Bridge security and liquidity fragmentation
- Solutions: Improved bridge technology and cross-chain protocols
Real-World Assets
Tokenisation of real-world assets is expanding protocol lending collateral:
- Assets: Real estate, commodities, and traditional securities
- Opportunities: New lending markets and yield sources
- Regulation: Requires clear regulatory frameworks
- Infrastructure: Oracles and legal frameworks for asset tokenisation
Building a DeFi Lending Portfolio
Portfolio Allocation Strategies
Structure your smart contract lending portfolio for optimal risk-return:
- Conservative (60%): Stablecoins on established protocols (Aave, Compound)
- Moderate (30%): Blue-chip tokenised lending (ETH, WBTC)
- Aggressive (10%): High-yield opportunities and new protocols
- Rebalancing: Review and adjust allocation quarterly
Risk Assessment Framework
Evaluate lending opportunities systematically:
- Protocol Risk: Audit history, team, and track record
- Asset Risk: Volatility, liquidity, and correlation
- Market Risk: Interest rate changes and market conditions
- Technical Risk: Smart contract complexity and dependencies
Performance Monitoring
Track your blockchain lending performance effectively:
- Yield Tracking: Monitor APY changes and compound returns
- Risk Metrics: Track volatility and maximum drawdown
- Gas Costs: Factor transaction costs into return calculations
- Tax Implications: Maintain records for tax reporting
Advanced DeFi Lending Tools and Analytics
Portfolio Management Tools
Use specialised tools to manage your digital asset lending positions:
- DefiLlama: Track total value locked and protocol rankings
- Zapper: Portfolio management and yield farming dashboard
- DeBank: Comprehensive DeFi portfolio tracking
- Zerion: Mobile-first DeFi portfolio management
- Revert Finance: Impermanent loss tracking and yield analysis
Yield Optimisation Strategies
Maximise returns through strategic yield optimisation:
- Rate Shopping: Compare rates across protocols regularly
- Incentive Hunting: Target protocols with token rewards
- Compound Strategies: Reinvest rewards for compound growth
- Arbitrage Opportunities: Exploit rate differences between protocols
- Seasonal Patterns: Understand cyclical yield patterns
Risk Monitoring Systems
Implement comprehensive risk monitoring for DeFi positions:
- Price Alerts: Set alerts for collateral ratio changes
- Protocol Monitoring: Track protocol health and governance changes
- Liquidation Alerts: Early warning systems for liquidation risk
- Gas Price Tracking: Monitor network congestion and fees
- Security Feeds: Stay informed about security incidents
DeFi Lending Market Analysis
Market Size and Growth
The blockchain lending market has experienced explosive growth:
- Total Value Locked: about $40bn across the lending category (DeFiLlama, 4 August 2026)
- Growth Path: DeFi TVL fell about 77% from its December 2021 peak before recovering through 2023 and 2024
- Protocol Diversity: 100+ lending protocols across multiple chains
Competitive Landscape
Understanding the competitive dynamics in blockchain lending:
- Market Leaders: Aave leads with roughly a third of lending TVL and Morpho is second at about a fifth; Compound has slipped out of the top five (DeFiLlama, 4 August 2026)
- Emerging Protocols: Euler, Fluid and others gaining traction
- Specialisation: Protocols focusing on specific assets or use cases
- Innovation: New features like flash loans and credit delegation
Interest Rate Dynamics
Factors influencing protocol-based lending rates:
- Supply and Demand: Basic economics drive rate changes
- Utilisation Rates: Higher utilisation leads to higher rates
- Token Incentives: Protocol rewards can boost effective yields
- Market Conditions: Bull/bear markets affect lending demand
- Regulatory Events: Policy changes impact market dynamics
Common Mistakes and How to Avoid Them
Beginner Mistakes
Avoid these common pitfalls when starting peer-to-peer lending:
- Insufficient Gas: Always keep extra ETH for transaction fees
- FOMO Investing: Don't chase unsustainably high yields
- Poor Research: Always audit protocols before depositing
- Overexposure: Don't put all funds in a single protocol
- Ignoring Risks: Understand all risks before investing
Advanced Mistakes
Even experienced users can make these errors:
- Leverage Addiction: Excessive leverage increases liquidation risk
- Yield Chasing: Constantly moving funds for marginal gains
- Ignoring Taxes: Poor record keeping for tax reporting
- Protocol Concentration: Too much exposure to single protocols
- Timing Mistakes: Poor entry/exit timing in volatile markets
Risk Management Failures
Critical risk management mistakes to avoid:
- No Exit Strategy: Always have clear exit criteria
- Inadequate Monitoring: Regular position monitoring is essential
- Emotional Decisions: Stick to predetermined strategies
- Insufficient Diversification: Spread risk across protocols and assets
- Ignoring Correlations: Understand asset correlations in portfolios
Conclusion
Protocol lending represents a paradigm shift in how we think about borrowing and lending money. With yields often exceeding those of traditional savings accounts and the ability to access global liquidity 24/7, peer-to-peer lending presents compelling opportunities for both conservative and aggressive investors.
The key to success in protocol lending lies in education, risk management, and gradual exposure. Start with small amounts on established protocols like Aave or Compound, understand the underlying mechanics, and slowly expand your knowledge and positions as you gain confidence.
Whilst protocol lending offers unprecedented opportunities, it also requires active management and continuous learning. Stay informed about protocol updates, security developments, and regulatory changes that could affect your positions.
As the DeFi ecosystem continues to mature, we can expect more sophisticated lending products, better user experiences, and increased institutional adoption. The integration of real-world assets, cross-chain functionality, and improved security measures will likely make peer-to-peer lending even more attractive and accessible.
The future of blockchain lending looks bright, with innovations like zero-knowledge proofs for privacy, account abstraction for better UX, and AI-powered risk management on the horizon. These developments will likely make blockchain lending more secure, efficient, and user-friendly.
For those willing to navigate the learning curve and manage the associated risks, peer-to-peer lending offers unprecedented opportunities to earn yield on cryptocurrency holdings while participating in the future of finance. Start small, learn continuously, and always prioritise security and risk management in your peer-to-peer lending journey.
The regulatory landscape for DeFi lending will continue to evolve, with clearer frameworks likely to emerge that balance innovation with consumer protection. This regulatory clarity will encourage further institutional adoption and improve the overall security and reliability of DeFi lending platforms, making them more attractive to mainstream investors.
Risk management tools and insurance products for DeFi lending are becoming more sophisticated, providing additional layers of protection for participants. These developments, combined with improved user interfaces and educational resources, will make DeFi lending more accessible to a broader audience while maintaining the core benefits of decentralisation and transparency.
The integration of artificial intelligence and machine learning into DeFi protocols will enable more sophisticated risk assessment, dynamic interest rate models, and automated portfolio management. These technological advances will help optimise returns while minimising risks, making DeFi lending more efficient and user-friendly for participants at all levels.
Sources & References
Frequently Asked Questions
- What is tokenised lending?
- Tokenised lending is the practice of lending and borrowing cryptocurrencies through decentralised protocols built on blockchain networks. It eliminates intermediaries like banks, allowing users to interact directly with smart contracts for transparent, permissionless lending and borrowing.
- Is digital asset lending safe?
- Digital asset lending carries risks including smart contract vulnerabilities, liquidation risk, and protocol exploits. However, established protocols like Aave and Compound have strong security track records. Always start with small amounts, use audited protocols, and diversify across multiple platforms.
- How much can I earn from protocol-based lending?
- Yields vary by asset and protocol. Stablecoins typically offer 3-8% APY on established protocols, while volatile assets can offer higher yields but with increased risk. Rates fluctuate based on supply and demand dynamics.
- What are the main risks of digital asset lending?
- Main risks include smart contract bugs, liquidation risk for borrowers, impermanent loss for liquidity providers, protocol governance risks, and market volatility. Always research protocols thoroughly and never invest more than you can afford to lose.
- Do I need technical knowledge to start blockchain lending?
- Basic understanding is sufficient to start. You need to know how to use a crypto wallet (like MetaMask), understand gas fees, and follow protocol instructions. Start with user-friendly protocols like Aave or Compound, which have intuitive interfaces.
- What's the difference between protocol-based lending and traditional lending?
- Protocol-based lending is permissionless (no credit checks), transparent (all transactions on-chain), operates 24/7 globally, and typically offers higher yields. Traditional lending requires credit checks, has limited hours, and involves intermediaries like banks.
- How do I choose a digital asset lending protocol?
- Consider factors like total value locked (TVL), security audits, track record, supported assets, interest rates, and community reputation. Start with established protocols like Aave, Compound, or Sky that have proven security and reliability.
- Are blockchain lending earnings taxable?
- Yes, in most jurisdictions. Interest earned from blockchain lending is typically taxed as ordinary income when received. Consult a tax professional familiar with cryptocurrency taxation in your jurisdiction for specific guidance.
Related Guides
← Back to Crypto Investing Blog Index
Financial Disclaimer
This content is not financial advice. All information provided is for educational purposes only. Cryptocurrency investments carry significant investment risk, and past performance does not guarantee future results. Always do your own research and consult a qualified financial advisor before making investment decisions.