DeFi vs CeFi Lending: Complete Guide
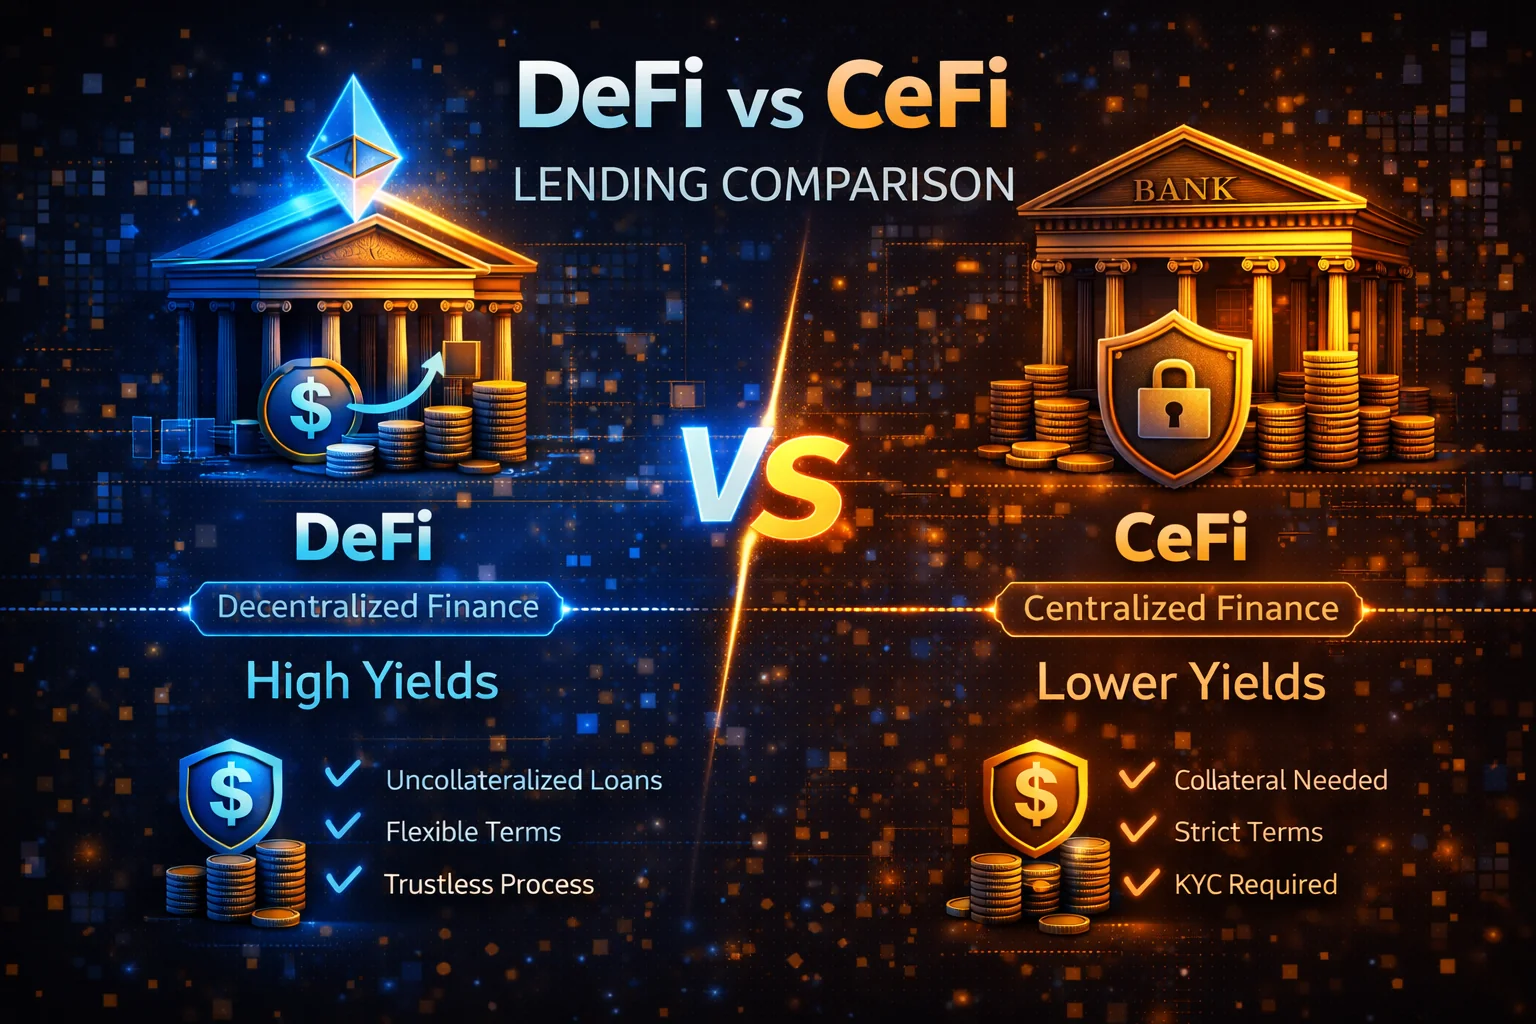
Cryptocurrency lending has evolved into two distinct approaches: Decentralised Finance (DeFi) protocols that operate through smart contracts and Centralised Finance (CeFi) platforms that function like traditional financial institutions. Each approach offers unique advantages and risks that significantly impact your potential returns, security, and overall lending experience.
DeFi lending protocols like Aave, Compound, and Sky (formerly MakerDAO) eliminate intermediaries by using smart contracts to automatically match lenders with borrowers, often providing higher yields and complete transparency. Surviving CeFi platforms such as Nexo and exchange-based earn programmes (Coinbase, Binance, OKX) offer more familiar user experiences with customer support and regulatory engagement — engagement that varies: Nexo holds no MiCA CASP authorisation of its own and serves the EEA through licensed partners, where the exchange programmes run on the exchange's own permissions, but require trusting centralised entities with your funds — a trust that BlockFi, Celsius, Voyager and several other CeFi lenders failed to honour during the 2022-2023 wave of bankruptcies covered later on this page.
This comprehensive guide examines every aspect of DeFi vs CeFi lending, comparing interest rates, security models, risk profiles, and user experiences. We'll analyse real-world performance data, explore the latest developments in both sectors, and provide practical strategies for optimising your lending approach based on your risk tolerance and investment goals.
Introduction
Crypto lending now runs on two models. The first is decentralised finance, or DeFi. Protocols such as Aave, Compound and Sky lend through smart contracts. You keep custody of your coins. The rate is set by an algorithm, based on how much of the pool is borrowed. Every balance is visible on-chain, all the time.
The second is centralised finance, or CeFi. Platforms such as Nexo, and the earn programmes of the large exchanges, take custody of your deposit. They pay a rate they set themselves. Between you and the market sit a company, a support desk and a set of terms. That is the trade: convenience for trust.
Neither model is the safe one. DeFi removes the counterparty. It adds smart-contract risk, oracle risk and, if you bridge assets, bridge risk. CeFi removes the technical work. It adds the risk that the company fails. The bankruptcies of BlockFi, Celsius, Voyager and Genesis in 2022 and 2023 showed what that looks like. Deposits were frozen. Some were never fully returned.
Rates behave differently too. A DeFi rate moves block by block as demand changes. It can double in a week when a pool runs hot. A CeFi rate is set by the platform. It changes when the platform decides, and usually with notice. Neither is a promise. Both can fall or rise while your position is open.
Insurance is the claim to read most carefully. Some CeFi platforms advertise cover. In practice that cover usually belongs to a custodian, not the platform. It answers theft from cold storage. It does not answer the platform becoming insolvent, which is the failure that emptied Celsius. DeFi has no insurer at all, unless you buy cover separately from a protocol such as Nexus Mutual.
This guide compares the two on the things that decide your outcome. It covers custody, security, rates, user experience and risk. It looks at the platforms that survived 2022. It sets out a decision framework for splitting a lending portfolio between the two models. It also explains what regulation actually requires of each, because the marketing word 'regulated' hides more than it tells.
Two newer layers sit on top of both. Liquid staking turns staked ETH into a token you can lend. Restaking lends that token's security out again. Each adds yield. Each adds a new way to lose money. Treat them as a third category with its own risks, not as a bonus on the first two.
One rule applies everywhere. Never lend more than you can afford to lose. Spread your lending across platforms, so that one failure is not the whole position. Read the terms before every new deposit, not after.
Quick Summary
DeFi lending offers transparency and self-custody through smart contracts, while CeFi lending provides user-friendly interfaces and customer support through centralised platforms. Both have distinct advantages and risks.
Key differences at a glance
- Control: DeFi = self-custody, CeFi = platform custody
- Transparency: DeFi = on-chain data, CeFi = platform disclosures
- Complexity: DeFi = technical knowledge required, CeFi = user-friendly
- Risks: DeFi = smart contract risks, CeFi = counterparty risks
Understanding DeFi vs CeFi Models
What is DeFi Lending?
Decentralised Finance (DeFi) lending operates through smart contracts on blockchain networks, primarily Ethereum. Users interact directly with protocols like Aave and Compound, as well as newer platforms, without intermediaries.
Key DeFi Characteristics:
- Smart contract automation: Lending and borrowing governed by code
- Self-custody: Users maintain control of their private keys
- Algorithmic rates: Interest rates adjust automatically based on supply and demand
- Composability: Protocols can interact with each other
- Global access: Available 24/7 without geographic restrictions
What is CeFi Lending?
Centralised Finance (CeFi) lending operates through traditional company structures, offering crypto lending services through platforms like Nexo, OKX, and Coinbase.
Key CeFi Characteristics:
- Custodial services: Platform holds and manages user funds
- User-friendly interfaces: Simple web and mobile applications
- Customer support: Human assistance and dispute resolution
- Regulatory compliance: Licensed and regulated in various jurisdictions
- Insurance options: Some platforms offer deposit protection
Technical Architecture Comparison
DeFi Technical Infrastructure
DeFi lending protocols operate as autonomous systems with several key components:
Smart Contract Components
- Lending pools: Contracts that hold deposited assets and track balances
- Interest rate models: Algorithms that calculate rates based on utilisation
- Liquidation engines: Automated systems for managing undercollateralised positions
- Oracle integrations: Price feeds for asset valuation and risk management
- Governance modules: decentralised decision-making mechanisms
Aave Protocol Example
- aTokens: Interest-bearing tokens representing deposits (e.g., aUSDC)
- Variable debt tokens: Represent variable rate borrowing positions
- No stable debt tokens: stable-rate borrowing was disabled in November 2023 and removed in V3.2
- Rate strategy contracts: Define interest rate curves for each asset
- Price oracle: Chainlink integration for reliable price feeds
CeFi Technical Infrastructure
CeFi platforms use traditional technology stacks with crypto integrations:
Core System Components
- User management: KYC/AML systems and account management
- Custody solutions: Hot and cold wallet management systems
- Risk management: Credit scoring and portfolio monitoring
- Matching engines: Systems for pairing lenders with borrowers
- Compliance tools: Regulatory reporting and monitoring
Nexo Platform Example
- Multi-signature wallets: Enhanced security for fund custody
- Real-time auditing: Continuous monitoring of asset reserves
- Custody cover: the custodians' own (Ledger's pooled programme, placed at Lloyd's); Nexo publishes no figure — custodian theft only, not deposit insurance
- Regulatory compliance: EU licensing and SOC 2 certification
- API infrastructure: Institutional-grade connectivity
Operational Models Deep Dive
DeFi Lending Mechanics
Interest Rate Calculation
DeFi protocols use mathematical models to determine rates:
- Utilisation rate: U = Total Borrowed / Total Supplied
- Base rate: Minimum rate when utilisation is 0%
- Slope parameters: Rate increase factors based on utilisation
- Optimal utilisation: Target utilisation rate (typically 80-90%)
Illustrative rate calculation (parameters differ per asset and move with governance):
- Base rate: 0%
- Slope 1: 4% (0% to 80% utilisation)
- Slope 2: 75% (80% to 100% utilisation)
- At 85% utilisation: 0% + (80% × 4%) + (5% × 75%) = 6.95%
Liquidation Process
- Health factor monitoring: Continuous tracking of collateral ratios
- Liquidation threshold: Predetermined ratios triggering liquidation
- Liquidation bonus: Incentive for liquidators (typically 5-10%)
- Partial liquidations: Only liquidate enough to restore health
CeFi Lending Operations
Credit Assessment Process
- Collateral evaluation: Asset quality and volatility assessment
- Loan-to-value ratios: Conservative ratios based on asset risk
- Credit scoring: User history and behaviour analysis
- Risk-based pricing: Interest rates adjusted for borrower risk
Fund Management Strategy
- Reserve requirements: Maintaining liquidity for withdrawals
- Diversification: Spreading risk across multiple borrowers
- Hedging strategies: Managing market risk exposure
- Yield optimisation: Active management of lending portfolios
Comprehensive Comparison
Security and Custody
| Aspect | DeFi Lending | CeFi Lending |
|---|---|---|
| Custody Model | Self-custody via smart contracts | Platform custody |
| Private Keys | User controls private keys | Platform controls private keys |
| Counterparty Risk | Eliminated (trustless) | Platform solvency risk |
| Smart Contract Risk | High (code vulnerabilities) | Low (platform manages) |
| Regulatory Risk | Protocol-level changes | Platform compliance issues |
User Experience and Accessibility
- Setup complexity: DeFi requires a wallet, gas fees, and protocol knowledge; CeFi needs only an email and KYC verification
- Technical knowledge: DeFi requires significant technical understanding; CeFi requires minimal
- Customer support: DeFi relies on community forums; CeFi provides dedicated support teams
- Mobile access: DeFi uses wallet apps; CeFi offers native mobile applications
- Fiat integration: DeFi has limited fiat on-ramps; CeFi offers extensive fiat integration
Interest Rates and Returns
| Rate Factor | DeFi | CeFi |
|---|---|---|
| Rate Setting | Algorithmic (utilisation curves) | Platform-determined |
| Rate Updates | Real-time (every block) | Periodic adjustments |
| Additional Rewards | Governance tokens | Platform tokens/promotions |
| Rate Transparency | Fully transparent | Platform-dependent |
| Typical range | 2-15% (highly variable) | 2-10% (more stable) |
Comprehensive Risk Analysis
DeFi Lending Risks
Smart Contract Risks
- Code vulnerabilities: Bugs can lead to fund loss or protocol exploitation
- Upgrade risks: Protocol changes may introduce new vulnerabilities
- Composability risks: Failures in connected protocols can cascade
- Oracle manipulation: Price feed attacks can trigger liquidations
Historical Smart Contract Failures
| Protocol | Year | Loss Amount | Cause |
|---|---|---|---|
| bZx | 2020 | $8M | Flash loan attack |
| Cream Finance | 2021 | $130M | Price oracle manipulation |
| Euler Finance | 2023 | $197M | Donation attack vulnerability |
| Hundred Finance | 2023 | $7M | Price manipulation |
Risk Mitigation Strategies for DeFi
- Protocol selection: Use only audited protocols with long track records
- Diversification: Spread funds across multiple protocols
- Insurance coverage: Consider Nexus Mutual or similar protection
- Position sizing: Limit exposure to any single protocol
- Monitoring tools: Use DeFiSafety scores and real-time alerts
Market and Liquidity Risks
- Impermanent loss: For liquidity providers in AMM pools
- Slippage: Large withdrawals may face price impact
- Gas fee volatility: High network congestion increases costs
- Governance attacks: Malicious proposals could harm the protocol
Gas Fee Impact Analysis
Transaction costs significantly affect DeFi profitability:
- Typical 2026 conditions (well under 1 gwei): deposits and withdrawals cost cents — Etherscan showed 0.15 gwei on 27 September 2026
- Busy periods (5-20 gwei): a few dollars each
- Congestion spikes (50+ gwei): $10-40 each
- The 2021-era extremes (300+ gwei, $100+ per transaction) have not recurred, but nothing prevents them
Break-even Analysis for DeFi
- Minimum position size: $2,000-5,000 to justify gas costs
- Hold period: Minimum 3-6 months for cost amortisation
- Rate premium required: 2-5% above CeFi to compensate for risks
- Layer 2 alternatives: Polygon, Arbitrum for lower costs
CeFi Lending Risks
Counterparty Risks
- Platform insolvency: Company bankruptcy could freeze funds
- Mismanagement: Poor risk management or fraud
- Rehypothecation: Platform lending out user deposits
- Withdrawal restrictions: Temporary or permanent freezes
Major CeFi Platform Failures
| Platform | Year | User Impact | Primary Cause |
|---|---|---|---|
| Celsius | 2022 | $4.7B frozen | Liquidity crisis, poor risk management |
| BlockFi | 2022 | $1B+ affected | FTX exposure, bankruptcy |
| Voyager | 2022 | ~$1.3B customer assets frozen | $650M+ Three Arrows exposure, liquidity issues |
| FTX | 2022 | $8B+ missing | Fraud, misuse of customer funds |
Warning Signs for CeFi Platforms
- Withdrawal delays: Unusual processing times or restrictions
- Rate cuts: Sudden, significant reductions in offered rates
- Communication issues: Reduced transparency or evasive responses
- Regulatory problems: Enforcement actions or licence issues
- Executive departures: Key personnel leaving unexpectedly
- Audit delays: Missing or delayed financial audits
Regulatory and Operational Risks
- Regulatory changes: New laws could affect operations
- Geographic restrictions: Service limitations by jurisdiction
- Technical failures: System outages or security breaches
- Policy changes: Unilateral changes to terms and rates
Regulatory Risk Assessment by Jurisdiction
- European Union: High regulatory clarity (MiCA), low risk — comprehensive framework with consumer protection
- United States: Medium regulatory clarity, medium risk — state-by-state variation with federal uncertainty
- Singapore: High regulatory clarity, low risk — clear licensing framework with pro-innovation stance
- United Kingdom: Medium regulatory clarity, medium risk — evolving framework with FCA oversight
Comparative Risk Assessment
Risk Matrix Analysis
| Risk Category | DeFi Impact | CeFi Impact | Mitigation Difficulty |
|---|---|---|---|
| Technology Risk | High | Medium | High (DeFi), Medium (CeFi) |
| Counterparty Risk | Low | High | Low (DeFi), High (CeFi) |
| Regulatory Risk | Medium | High | Medium (both) |
| Liquidity Risk | Medium | Medium | Medium (both) |
| Operational Risk | High | Low | High (DeFi), Low (CeFi) |
Risk-Adjusted Return Expectations
Considering risks, expected returns should be adjusted:
- DeFi protocols: Require 2-5% premium over CeFi for additional risks
- New DeFi protocols: Require 5-10% premium for unproven track record
- Regulated CeFi: Accept 1-3% lower rates for reduced risk
- Unregulated CeFi: Require 3-7% premium for regulatory uncertainty
Leading Platforms
Top DeFi Lending Protocols
Aave
- Features: Multi-chain support, flash loans, E-Mode for correlated assets
- Assets: 30+ cryptocurrencies
- Innovation: Credit delegation, isolation mode
- Security: Multiple audits, bug bounty program
Compound
- Features: Algorithmic interest rates; Compound III lends one base asset per market against listed collateral
- Assets: Major cryptocurrencies and stablecoins
- Governance: COMP token holders vote on changes
- Track record: One of the oldest DeFi protocols
Newer Protocols
- Euler: Permissionless listing, advanced risk management
- Morpho: optimised rates through peer-to-peer matching
- Fluid: High-efficiency lending and DEX liquidity layer
Top CeFi Lending Platforms
Nexo
- Regulation: registrations in several jurisdictions, no MiCA authorisation of its own; SOC 2 Type 2 audited
- Custodial-hack cover: ~$775M (a 2022–23 figure) via custody partners' Lloyd's policy — custodian theft only, not deposit insurance
- Features: Instant loans, credit cards, high-yield accounts
- Assets: 100+ cryptocurrencies and fiat currencies
Major Exchanges
- Binance Earn: Largest selection, flexible and locked products
- Coinbase: US-regulated, institutional-grade security
- Kraken: Strong security record, transparent operations
- OKX: Competitive rates, global accessibility
How to Choose: Decision Framework
Choose DeFi If You:
- Value transparency and want to verify all protocol operations
- Prefer self-custody and control over your private keys
- Have technical knowledge to navigate wallets and protocols safely
- Want access to the latest innovations and highest potential yields
- Are comfortable with smart contracts and technical risks
- Don't need customer support or dispute resolution
Choose CeFi If You:
- Prioritise ease of use and familiar interfaces
- Want customer support and dispute resolution options
- Prefer regulated platforms with compliance oversight
- Need fiat currency integration and banking features
- Value the platform-specific insurance cover some CeFi services carry (custodian cover, not deposit insurance)
- Are new to crypto and prefer guided experiences
Hybrid Strategy
Many experienced users employ a hybrid approach:
- 60% CeFi: Core holdings on regulated platforms for stability
- 30% DeFi: Higher-risk, higher-reward opportunities
- 10% Experimental: New protocols and strategies
Risk-Based Allocation
| Risk Tolerance | Recommended Split | Focus Areas |
|---|---|---|
| Conservative | 80% CeFi, 20% DeFi | Regulated platforms, established protocols |
| Moderate | 60% CeFi, 40% DeFi | Mix of safety and opportunity |
| Aggressive | 40% CeFi, 60% DeFi | Yield optimisation, new protocols |
Best Practices for Both Models
General Security Practices
- Start small: Test platforms with small amounts first
- Diversify: Don't put all funds on a single platform or protocol
- Research thoroughly: Understand risks before depositing
- Monitor regularly: Check rates, platform health, and news
- Keep records: Track transactions for tax and analysis purposes
DeFi-Specific Practices
- Use hardware wallets: For large amounts and long-term storage
- Verify contracts: Check official addresses and audit reports
- Understand gas costs: Factor transaction fees into returns
- Monitor governance: Stay informed about protocol changes
- Have exit strategies: Know how to withdraw quickly if needed
CeFi-Specific Practices
- Check regulations: Ensure platform is licensed in your jurisdiction
- Read terms carefully: Understand withdrawal limits and conditions
- Verify insurance: Check coverage details and limitations
- Monitor platform health: Watch for signs of financial stress
- Use strong security: Enable 2FA and use unique passwords
Advanced Strategies and Portfolio Optimisation
Multi-Protocol Yield Optimisation
Dynamic Rate Arbitrage
Sophisticated users can exploit rate differences between platforms:
- Rate monitoring: Track rates across 10+ platforms in real-time
- Automated rebalancing: Use tools like DeFiSaver or Instadapp
- Gas cost optimisation: Time moves during low congestion periods
- Minimum thresholds: Only move for >2% rate differences
Cross-Chain Yield Farming
- Ethereum (Aave, Compound): utilisation-set rates (not quoted); transaction cost cents at 2026 gas prices
- Polygon (Aave): rates not quoted; cents per transaction
- Arbitrum (Aave): rates not quoted; cents per transaction
- Avalanche (Benqi, Aave): rates not quoted; cents per transaction
Risk-Parity Portfolio Construction
Equal Risk Contribution Model
Allocate based on risk contribution rather than capital amount:
Sample Risk-Parity Allocation
- 40% Tier 1 CeFi (Nexo, Coinbase): Low risk, stable returns
- 30% Blue-chip DeFi (Aave, Compound): Medium risk, higher returns
- 20% Layer 2 DeFi (Polygon, Arbitrum): Medium-high risk, cost efficiency
- 10% Emerging protocols: High risk, highest potential returns
Correlation-Based Diversification
- US CeFi: High market correlation, low tech correlation, high regulatory correlation
- EU CeFi: High market correlation, low tech correlation, medium regulatory correlation
- Ethereum DeFi: Medium market correlation, high tech correlation, low regulatory correlation
- Alt-chain DeFi: Medium market correlation, medium tech correlation, low regulatory correlation
Automated Strategy Implementation
DeFi Automation Tools
- Yearn Finance: Automated vault strategies with auto-compounding
- Harvest Finance: Yield farming optimisation across protocols
- Beefy Finance: Multi-chain yield optimisation
- DeFiSaver: Position management and automation
CeFi API Integration
- Rate monitoring: Automated tracking of platform rates
- Rebalancing alerts: Notifications for significant rate changes
- Portfolio tracking: Consolidated view across platforms
- Tax reporting: Automated transaction logging
Advanced Risk Management
Dynamic Hedging Strategies
- Stablecoin focus: Reduce crypto price exposure during volatility
- Correlation hedging: Balance correlated and uncorrelated positions
- Temporal diversification: Stagger entry and exit timing
- Liquidity laddering: Maintain positions with different lockup periods
Stress Testing Framework
- Market crash (-50%): DeFi faces high liquidations and gas spikes; CeFi faces withdrawal restrictions. Response: reduce leverage and increase stablecoin allocation
- Regulatory crackdown: DeFi faces protocol restrictions; CeFi faces platform shutdowns. Response: geographic diversification
- Major hack: DeFi faces protocol-specific losses; CeFi faces platform-wide impact. Response: immediate diversification review
- Interest rate spike: DeFi faces increased borrowing costs; CeFi faces competitive pressure. Response: rebalance to higher-yielding options
Outlook and Trends
DeFi Evolution
- Improved security: Better auditing tools and formal verification
- Cross-chain expansion: More protocols supporting multiple blockchains
- Institutional adoption: Professional-grade interfaces and compliance tools
- Insurance integration: Built-in coverage for smart contract risks
CeFi Maturation
- Regulatory clarity: Clearer frameworks in major jurisdictions
- Enhanced transparency: Real-time proof-of-reserves
- Better insurance: Comprehensive coverage options
- DeFi integration: Platforms offering access to DeFi protocols
Convergence Trends
- Hybrid platforms: CeFi interfaces with DeFi backends
- Institutional DeFi: Compliant protocols for institutional users
- Cross-platform tools: Unified interfaces for both models
- Standardised reporting: Common metrics and transparency standards
What Regulation Actually Requires
The numbers that circulate for 'crypto lending capital requirements' are mostly invented. Here is what the rules say. In the EU, MiCA — Regulation (EU) 2023/1114 — authorises crypto-asset service providers. Article 67 sets their prudential floor. A provider must hold permanent minimum capital of €50,000, €125,000 or €150,000, depending on the class of service; custody and exchange sit in the €125,000 class. If one quarter of the previous year's fixed overheads is higher, that figure applies instead. The requirement can be met with own funds or an insurance policy. It is a solvency floor for the firm. It is not a guarantee for your deposit.
A CASP must also keep client crypto-assets separate from its own. Whether a platform holds a MiCA authorisation is checkable on ESMA's register. The register is public and searchable. A platform whose name is not on it is not MiCA-authorised, whatever its marketing says. The transitional period that let unauthorised firms keep operating ended on 30 June 2026. Nexo, for example, holds no authorisation of its own and serves EEA clients through licensed partners.
In the UK there is no crypto-specific capital regime yet for lending: firms need cryptoasset registration with the FCA for anti-money-laundering purposes and must comply with the financial-promotions rules, and none of that brings FSCS cover. Treat "regulated" in a CeFi platform's marketing as a question — regulated for what, by whom — rather than an answer. The FCA's cryptoasset register lists firms registered for anti-money-laundering supervision; registration is not authorisation and brings no FSCS cover.
DeFi protocols have no capital requirement because there is no firm: over-collateralisation is the whole safeguard. The parameters that matter — loan-to-value, liquidation threshold, liquidation bonus — are set per asset by governance and change. Read them live on the protocol's app before you rely on them; WBTC on Aave V3 Ethereum sat at 73% LTV and a 78% liquidation threshold on 22 September 2026, and a proposal to raise both was in governance that week.
Real-World DeFi vs CeFi Lending Comparisons
The cases below are illustrative: the users are invented and the rates are round numbers of the kind seen in calm markets, not readings.
Case 1: Conservative Lender - Stablecoin Yield
User: Risk-averse investor with $25,000 USDC
Goal: Earn passive income with minimal risk
Comparison:
- CeFi (Nexo): 8% APY illustrative, instant withdrawal, custody cover only at the custodian (not deposit insurance)
- DeFi (Aave): 5.2% APY, instant withdrawal, no insurance
- Risk Trade-off: CeFi offers higher yield but carries custodian and counterparty risk vs DeFi's lower yield with self-custody
Results After 12 Months:
- CeFi earnings: $2,000 (8% on $25k)
- DeFi earnings: $1,300 (5.2% on $25k)
- Difference: $700 more with CeFi (54% higher yield)
Decision: User chose CeFi for the higher rate, accepting counterparty risk with no deposit insurance behind it.
Case 2: Borrower - Collateralised Loan
User: ETH holder needing $50,000 liquidity
Collateral: 40 ETH (worth $80,000 at $2,000/ETH)
Comparison:
- CeFi (Nexo): capped at 50% LTV, so $40,000 against 40 ETH; standard 18.9% APR unless a loyalty tier and a far lower LTV earn less; KYC required; instant approval
- DeFi (Aave): 3.5% APR, 62.5% LTV, no KYC, instant
- Borrowing power: DeFi lends $50,000 on this collateral; Nexo's cap stops at $40,000
Annual Cost:
- CeFi: $7,560 interest (18.9% on $40k)
- DeFi: $1,750 interest (3.5% on $50k)
- Savings with DeFi: about $5,800 a year, on $10,000 more borrowed
Decision: User chose DeFi for lower rates and instant access, maintained self-custody of collateral.
Case 3: Yield Farmer - Leveraged Strategy
User: Experienced DeFi user with $100,000
Strategy: Recursive lending for amplified yield
The arithmetic first: a loop only pays when the yield on what you supply exceeds the rate on what you borrow. That is never true for the same asset in the same pool — supply APY is borrow APR times utilisation, less the reserve factor — so "deposit USDC, borrow USDC" loses money on every loop. It can work with staked ETH: supply wstETH earning roughly 2.5% staking yield, borrow ETH in E-Mode at a lower rate, repeat. The spread is a point or two, three loops turn a 3% move into liquidation, and one rate move flips the sign.
Lesson: compare the net spread after a rate move against a flat CeFi stablecoin rate before bothering; most of the time the flat rate wins on risk-adjusted terms.
Case 4: Privacy-Focused User - No KYC Lending
User: Privacy advocate with 5 BTC
Need: Borrow $50,000 without identity disclosure
Experience:
- CeFi Attempt: All platforms required full KYC, rejected due to privacy concerns
- DeFi Solution: Wrapped BTC on Ethereum, borrowed from Aave
- Privacy Benefit: DeFi enabled borrowing without identity verification
Results:
- Borrowed $50k USDC against 2.5 wBTC (50% LTV)
- Interest rate: 4.2% APR
- No KYC, no identity verification
- Full control of collateral keys
- Trade-off: Bridge risk, smart contract risk
Decision: DeFi was the only option for privacy-preserving lending, the user accepted technical risks.
Case 5: Institutional Borrower - Large-Scale Lending
User: Crypto fund needing $5M credit line
Collateral: $10M in BTC and ETH
Comparison:
- CeFi (post-2022 institutional venues — e.g. Anchorage Digital, FalconX, BitGo Prime; verify current standing before any allocation, since several previous-generation venues including Genesis and BlockFi exited the space in 2022-2024): Personalised rates, OTC desk, relationship manager
- DeFi (Aave/Compound): Algorithmic rates, no negotiation, self-service
- Service Level: CeFi provides institutional support vs DeFi's automated approach
Decision Factors:
- CeFi: Negotiated 6.5% APR (vs 8% standard)
- DeFi: Market rate 4.8% APR (non-negotiable)
- CeFi: Dedicated support, flexible terms
- DeFi: No support, rigid liquidation rules
Decision: Fund split: 60% DeFi (lower rates) + 40% CeFi (relationship, flexibility). Diversified counterparty risk.
Advanced Lending Ecosystem Analysis and Professional Implementation
Institutional DeFi vs CeFi Lending Strategies and Enterprise Integration
Professional lending ecosystem evaluation requires sophisticated analysis of institutional requirements, regulatory compliance frameworks, and operational efficiency considerations that enable enterprise-grade lending strategies while maintaining fiduciary responsibilities and stakeholder protection. Institutional lending strategies incorporate comprehensive due diligence procedures, advanced risk assessment methodologies, and sophisticated portfolio optimisation techniques that maximise returns while maintaining appropriate risk profiles for professional investment management and corporate treasury operations through lending excellence and institutional financial optimisation designed for enterprise cryptocurrency lending and professional asset management requirements.
Enterprise lending integration includes a comprehensive evaluation of DeFi protocol governance, CeFi platform regulatory compliance, and sophisticated operational procedures that enable systematic lending adoption while maintaining security standards and regulatory oversight. Professional enterprise operations utilise advanced analytics, comprehensive reporting systems, and sophisticated optimisation techniques that enable strategic lending integration while managing technical risks and operational complexity through institutional lending excellence and professional financial management designed for corporate lending optimisation and enterprise cryptocurrency strategies.
Quantitative Lending Analysis and Mathematical Risk Assessment
Advanced lending ecosystem analysis utilises sophisticated quantitative models, including comprehensive yield analysis, systematic risk assessment, and mathematical optimisation, that enable informed lending decisions while managing portfolio risks and operational requirements. Quantitative lending analysis incorporates advanced statistical techniques, sophisticated correlation modelling, and comprehensive backtesting frameworks that enable systematic lending evaluation while maintaining appropriate risk management and strategic positioning through mathematical excellence and professional quantitative analysis designed for institutional lending operations and yield optimisation.
Mathematical risk assessment includes implementation of advanced algorithms for optimal lending allocation, sophisticated risk measurement, and comprehensive performance attribution that maximise lending efficiency while maintaining security standards and operational reliability. Professional practitioners utilise advanced econometric models, comprehensive scenario analysis, and sophisticated optimisation techniques that enable continuous improvement in lending strategies while managing market volatility through quantitative excellence and professional optimisation designed for institutional lending operations and cryptocurrency yield generation excellence.
Technology Integration and Automated Lending Management
Modern lending operations utilise advanced technology, including sophisticated portfolio management systems, comprehensive automation platforms, and advanced analytics tools that optimise lending strategies while improving operational efficiency and risk management through technological excellence and innovation. Technology-enhanced lending management includes automated yield optimisation, sophisticated rebalancing systems, and comprehensive performance tracking that enable real-time lending oversight while maintaining strategic positioning and risk control through technological innovation and professional automation designed for advanced lending operations and institutional cryptocurrency management excellence.
Automated lending management includes the implementation of advanced algorithms for optimal platform selection, sophisticated risk monitoring systems, and comprehensive performance optimisation that maximise lending returns while minimising operational overhead and risk exposure through technological excellence. Professional technology integration requires advanced system architecture, comprehensive data management capabilities, and sophisticated analytical frameworks that enable continuous lending optimisation while maintaining security and operational excellence through technological innovation and professional automation designed for institutional lending management and cryptocurrency yield generation leadership in the evolving digital asset lending ecosystem.
Future Trends and Market Evolution
Future developments in DeFi and CeFi lending include hybrid platforms that place CeFi interfaces in front of DeFi backends, interoperability solutions that extend lending across multiple blockchains, and regulatory frameworks clear enough for regulated platforms to offer DeFi lending while maintaining security and compliance standards. These emerging trends encompass development of institutional-grade infrastructure, implementation of advanced custody solutions, and creation of comprehensive risk management frameworks that support lending ecosystem growth while addressing regulatory requirements and operational challenges through innovation and professional excellence.
Market evolution includes the development of sophisticated yield optimisation strategies, the implementation of advanced automated lending protocols, and the creation of comprehensive cross-platform integration solutions that maximise lending efficiency while maintaining security and operational requirements. Professional lending management requires understanding of emerging market dynamics, implementation of adaptive strategies, and development of comprehensive risk assessment frameworks that capitalise on evolving opportunities while managing regulatory changes and technological developments through professional excellence and institutional-grade lending operations.
Strategic positioning for future lending developments requires continuous monitoring of technological innovations, systematic evaluation of regulatory changes, and implementation of adaptive strategies that capitalise on emerging opportunities while managing evolving risks and compliance requirements. Professional lending ecosystem management includes development of comprehensive scenario planning, implementation of flexible operational frameworks, and creation of sophisticated adaptation mechanisms that ensure long-term lending success while maintaining competitive advantages and operational excellence in the rapidly evolving cryptocurrency lending landscape and digital asset yield generation ecosystem.
Institutional Lending and Professional Management
Institutional lending strategies encompass sophisticated portfolio management techniques, comprehensive risk assessment frameworks, and advanced compliance procedures that enable professional-grade lending operations while maintaining fiduciary responsibilities and regulatory adherence. Professional institutional lending includes implementation of comprehensive due diligence procedures, sophisticated performance monitoring systems, and advanced reporting frameworks that ensure optimal lending outcomes while maintaining transparency and accountability through institutional-grade lending management excellence.
Advanced institutional approaches include the development of comprehensive lending policies, the implementation of sophisticated risk management systems, and the creation of advanced performance attribution frameworks that optimise institutional lending strategies while maintaining prudent risk management and operational excellence. Professional institutional lending requires understanding of complex regulatory requirements, implementation of comprehensive compliance monitoring systems, and development of sophisticated reporting procedures that ensure regulatory adherence while maximising lending performance through institutional excellence and professional lending management designed for fiduciary success.
Institutional lending optimisation includes systematic evaluation of lending opportunities, implementation of advanced portfolio construction techniques, and development of comprehensive performance measurement systems that ensure optimal institutional lending outcomes while maintaining risk management and compliance requirements. Professional institutional management encompasses continuous monitoring of lending markets, systematic assessment of emerging opportunities, and implementation of adaptive strategies that capitalise on market developments while maintaining institutional standards and fiduciary excellence through professional lending management and institutional-grade operational procedures designed for long-term institutional lending success.
Advanced Lending Technology and Automation
Advanced lending technology encompasses sophisticated automated lending protocols, comprehensive smart contract implementations, and innovative yield optimisation algorithms that maximise lending efficiency while maintaining security and operational reliability. Professional lending technology includes development of comprehensive automated rebalancing systems, sophisticated risk monitoring frameworks, and advanced performance tracking solutions that enable optimal lending management while reducing operational overhead and human error through technological excellence and professional automation designed for institutional lending operations.
Automated lending management systems include the implementation of advanced machine learning algorithms, sophisticated predictive analytics frameworks, and comprehensive market analysis tools that optimise lending strategies while maintaining risk management and performance objectives. Professional lending automation requires understanding of complex market dynamics, implementation of sophisticated algorithmic trading strategies, and development of comprehensive monitoring systems that ensure optimal lending performance while maintaining security and operational excellence through technological innovation and professional automation designed for advanced lending management and cryptocurrency yield optimisation success in the evolving digital asset lending ecosystem.
Lending Performance Optimisation and Analytics
Advanced lending performance optimisation encompasses sophisticated analytics frameworks, comprehensive performance measurement systems, and innovative optimisation algorithms that maximise lending returns while maintaining risk management and operational efficiency. Professional performance optimisation includes implementation of advanced data analysis techniques, sophisticated benchmarking procedures, and comprehensive reporting systems that enable continuous improvement in lending strategies while maintaining transparency and accountability through analytical excellence and professional performance management designed for institutional lending success and cryptocurrency yield generation leadership in the competitive digital asset lending marketplace.
Conclusion
The choice between DeFi and CeFi lending ultimately depends on your risk tolerance, technical expertise, and investment objectives. Both approaches offer compelling advantages: CeFi provides user-friendly interfaces, customer support, and regulatory protection, while DeFi offers higher yields, complete transparency, and financial sovereignty through self-custody.
For most investors, a diversified approach proves most effective, utilising both DeFi and CeFi platforms to balance risk and reward. Start with CeFi platforms if you prioritise simplicity and security, then gradually explore DeFi protocols as you gain experience and confidence in managing smart contract risks and wallet security.
The regulatory landscape will continue to shape both sectors, with CeFi platforms likely benefiting from clearer compliance frameworks while DeFi protocols adapt to evolving regulatory requirements. This evolution creates opportunities for investors who understand the implications of regulatory changes and can position their lending strategies accordingly.
Risk management remains paramount in cryptocurrency lending, regardless of whether you choose DeFi or CeFi platforms. Diversification across multiple platforms, understanding the underlying risks of each approach, and never lending more than you can afford to lose are fundamental principles that apply to both ecosystems.
The future of cryptocurrency lending will likely see continued convergence between DeFi and CeFi approaches, with regulatory frameworks evolving to accommodate both models while protecting investors. Staying informed about these developments and adapting your lending strategy accordingly will be crucial for long-term success in this rapidly evolving space.
As the cryptocurrency lending landscape continues to evolve, the distinction between DeFi and CeFi is becoming increasingly blurred, with hybrid solutions emerging that combine the best of both worlds. Success in crypto lending requires staying informed about platform developments, understanding the risks involved, and maintaining proper diversification across multiple platforms and strategies. Whether you choose DeFi's innovation or CeFi's stability, the key is making informed decisions based on thorough research and your personal financial situation.
Sources & References
- DeFiLlama - Lending Protocols Analytics
- Aave Protocol - Official Documentation
- Compound Finance - DeFi Lending Platform
- EUR-Lex — Regulation (EU) 2023/1114 (MiCA), Article 67 and Annex IV
- FCA — cryptoasset AML/CTF registration regime
- Etherscan — Ethereum Gas Tracker (read 27 September 2026)
- Best Crypto Lending Platforms 2025
- How Secure Is Crypto Lending?
Frequently Asked Questions
- Is DeFi lending safer than CeFi lending?
- Neither is universally safer. DeFi eliminates counterparty risk but introduces risks from smart contracts and oracles. CeFi offers a simpler user experience but depends on platform solvency and governance.
- Which offers higher interest rates?
- Rates vary by market conditions. DeFi can offer higher rates during high-utilisation periods, while CeFi may offer competitive promotional rates with caps or lockup requirements.
- Which is more transparent?
- DeFi is generally more transparent with on-chain data and auditable smart contracts. CeFi transparency depends on platform disclosures and the quality of proof-of-reserves.
- Can I use both DeFi and CeFi lending?
- Yes, many users diversify across both models to balance convenience, transparency, and risk. This approach can reduce single-point-of-failure risks.
- What's the minimum amount to start?
- DeFi protocols typically have no minimums but require gas fees for transactions. CeFi platforms often have no minimums but may have caps on promotional rates.
- How do I track performance across both models?
- Use portfolio tracking tools like Zapper or DeBank for DeFi, and maintain spreadsheets or use platform APIs for CeFi. Consider net returns after fees and taxes.
- What happens during market crashes?
- Both models face stress during crashes. DeFi may see liquidation cascades and high gas fees, while CeFi platforms might impose withdrawal limits or freeze operations.
- Should beginners start with DeFi or CeFi?
- Beginners should typically start with CeFi for its user-friendly interface and support, then gradually explore DeFi as they gain experience and technical knowledge.
← Back to Crypto Investing Blog Index
Financial Disclaimer
This content is not financial advice. All information provided is for educational purposes only. Cryptocurrency investments carry significant investment risk, and past performance does not guarantee future results. Always do your own research and consult a qualified financial advisor before making investment decisions.